The 'Objective Market Analysis' Your Agent Ran on Your Home Is More Art Than Science
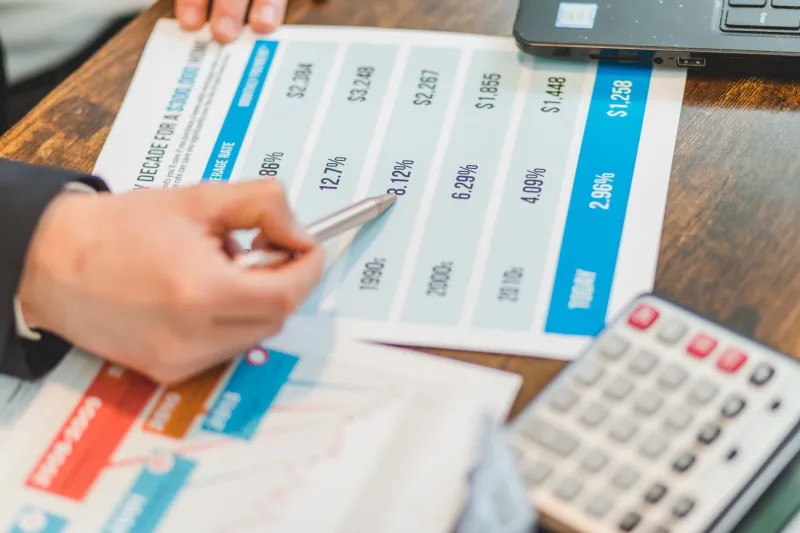
It arrives looking authoritative. A branded PDF, sometimes a glossy printout, with recent sale prices, market trends, and a recommended list price at the end. Your agent calls it a Comparative Market Analysis — a CMA — and presents it as the data-driven answer to what your home is worth.
The word analysis does a lot of persuasive work here. It implies methodology. Rigor. Something more like math than opinion.
The reality is that a CMA is a judgment-driven document built on a framework flexible enough that two experienced agents analyzing the same property, in the same week, with access to the same MLS data, can produce valuations that are $40,000 apart — and neither of them is technically wrong.
That's not a knock on agents. It's a description of how the process actually works.
The Building Blocks of a CMA
A Comparative Market Analysis works by identifying recently sold homes that are similar to the subject property — the home being evaluated — and using those sales as benchmarks. The agent then adjusts for differences between the comps and the subject property to arrive at an estimated market value.
On paper, this is a reasonable approach. In practice, every step of it involves decisions that can move the number significantly.
Which homes count as comparable? This is the first and most consequential question. Agents typically look for homes with similar square footage, bedroom and bathroom count, lot size, age, and condition, sold within a certain time window and geographic radius. But how similar is similar enough? A home 0.4 miles away versus 0.8 miles away. A sale from four months ago versus seven months ago. A house with a renovated kitchen versus one with original 1990s cabinetry. Every line you draw is a judgment call.
How far back do you look? In a stable market, agents might use sales from the past six months. In a fast-moving market, three months is more defensible. In a slow market with limited sales, you might have to go back a year. That time window affects which comparable sales are available — and which narrative the data supports.
How do you adjust for differences? If a comparable home sold for $480,000 and had a finished basement while your home doesn't, an agent might subtract $15,000 from that comp's value to make it more apples-to-apples. But where does that $15,000 figure come from? Experience. Local intuition. Sometimes a database of paired sales. Sometimes a number that felt right. There is no universal adjustment schedule.
Where the Bias Sneaks In
Here's the part that doesn't make it into the listing presentation.
Agents who are representing sellers have a natural incentive to produce CMAs that support higher list prices. Not because they're being dishonest — but because a higher suggested price makes the seller happy, wins the listing, and positions the agent as the one who "believes in" the property's value. The agent who comes in with the highest number often gets the job.
This creates a competitive dynamic where CMAs drift upward, homes get listed above realistic market value, and sellers are disappointed when offers don't materialize — or when the eventual accepted offer comes in well below the original list price.
On the buyer's side, buyer's agents have an incentive to produce CMAs that support the price their client wants to pay — or that justify making an offer competitive enough to win. Neither direction is necessarily dishonest. Both are influenced by something other than pure data.
Academic researchers have documented this pattern. Studies of listing agent CMAs consistently find that properties are initially priced above eventual sale prices at rates that suggest systematic optimism — or strategic inflation — in the valuation process.
The Same House, Different Numbers
If you've ever interviewed multiple agents before listing your home, you may have experienced this firsthand. Agent A comes in and suggests listing at $625,000. Agent B recommends $589,000. Agent C says $610,000 is the sweet spot. They all looked at the same house. They all had access to the same sold data.
The differences aren't random. They reflect which comps each agent selected, which adjustments they applied, how they weighted recent market trends, and — honestly — what they thought you wanted to hear.
This doesn't mean CMAs are worthless. It means they're estimates, not measurements. There's a difference, and it matters when you're deciding whether to list at $625,000 or $589,000.
What's Actually Changing
The tools available for market analysis are evolving, and that's worth noting. Automated Valuation Models — the algorithms behind Zillow's Zestimate, Redfin's Estimate, and similar tools — apply consistent methodology at scale and don't have a listing to win or a client to please. They have their own limitations (they can't see inside a home, can't account for recent renovations, and struggle in markets with limited sales data), but they offer a useful cross-check against agent-produced valuations.
Some brokerages are also investing in more rigorous internal valuation training, and the increased availability of transaction data through public records and MLS portals means consumers have more ability than ever to spot-check the comps their agent is using.
But the fundamental structure of the CMA — a judgment-driven document produced by someone with a financial interest in the outcome — hasn't changed. And it's unlikely to change dramatically anytime soon, because the flexibility in the methodology isn't a bug. It's what allows agents to adapt to the genuine complexity of local real estate markets.
How to Use a CMA Without Being Misled By It
The CMA is still a useful tool. Here's how to engage with it more critically:
Ask to see the raw comps, not just the summary. Look at which homes were selected and which were excluded. Ask why a particular sale wasn't included if you noticed it in your research.
Run your own rough analysis. Pull recent sales in your neighborhood on Zillow or Redfin before your agent meeting. You'll have a baseline that makes it easier to evaluate whether the agent's comp selection seems reasonable.
Be skeptical of the highest number. The agent recommending the highest list price isn't necessarily the best agent — they may simply be the most optimistic, or the most strategic about winning your listing.
Ask what the agent thinks the home will actually sell for, not just what they recommend listing it at. That's often a more honest number.
A Comparative Market Analysis is a starting point for a conversation about value, not the conclusion of one. The agents who are most useful to work with are usually the ones willing to explain their methodology, acknowledge uncertainty, and tell you something other than what you want to hear.
The real story: CMAs look like data science but operate more like informed opinion. The methodology is real, the local knowledge matters, and a good agent's analysis has genuine value — but the flexibility built into the process means the number you get reflects judgment as much as it reflects the market. Knowing that is the first step to using it well.